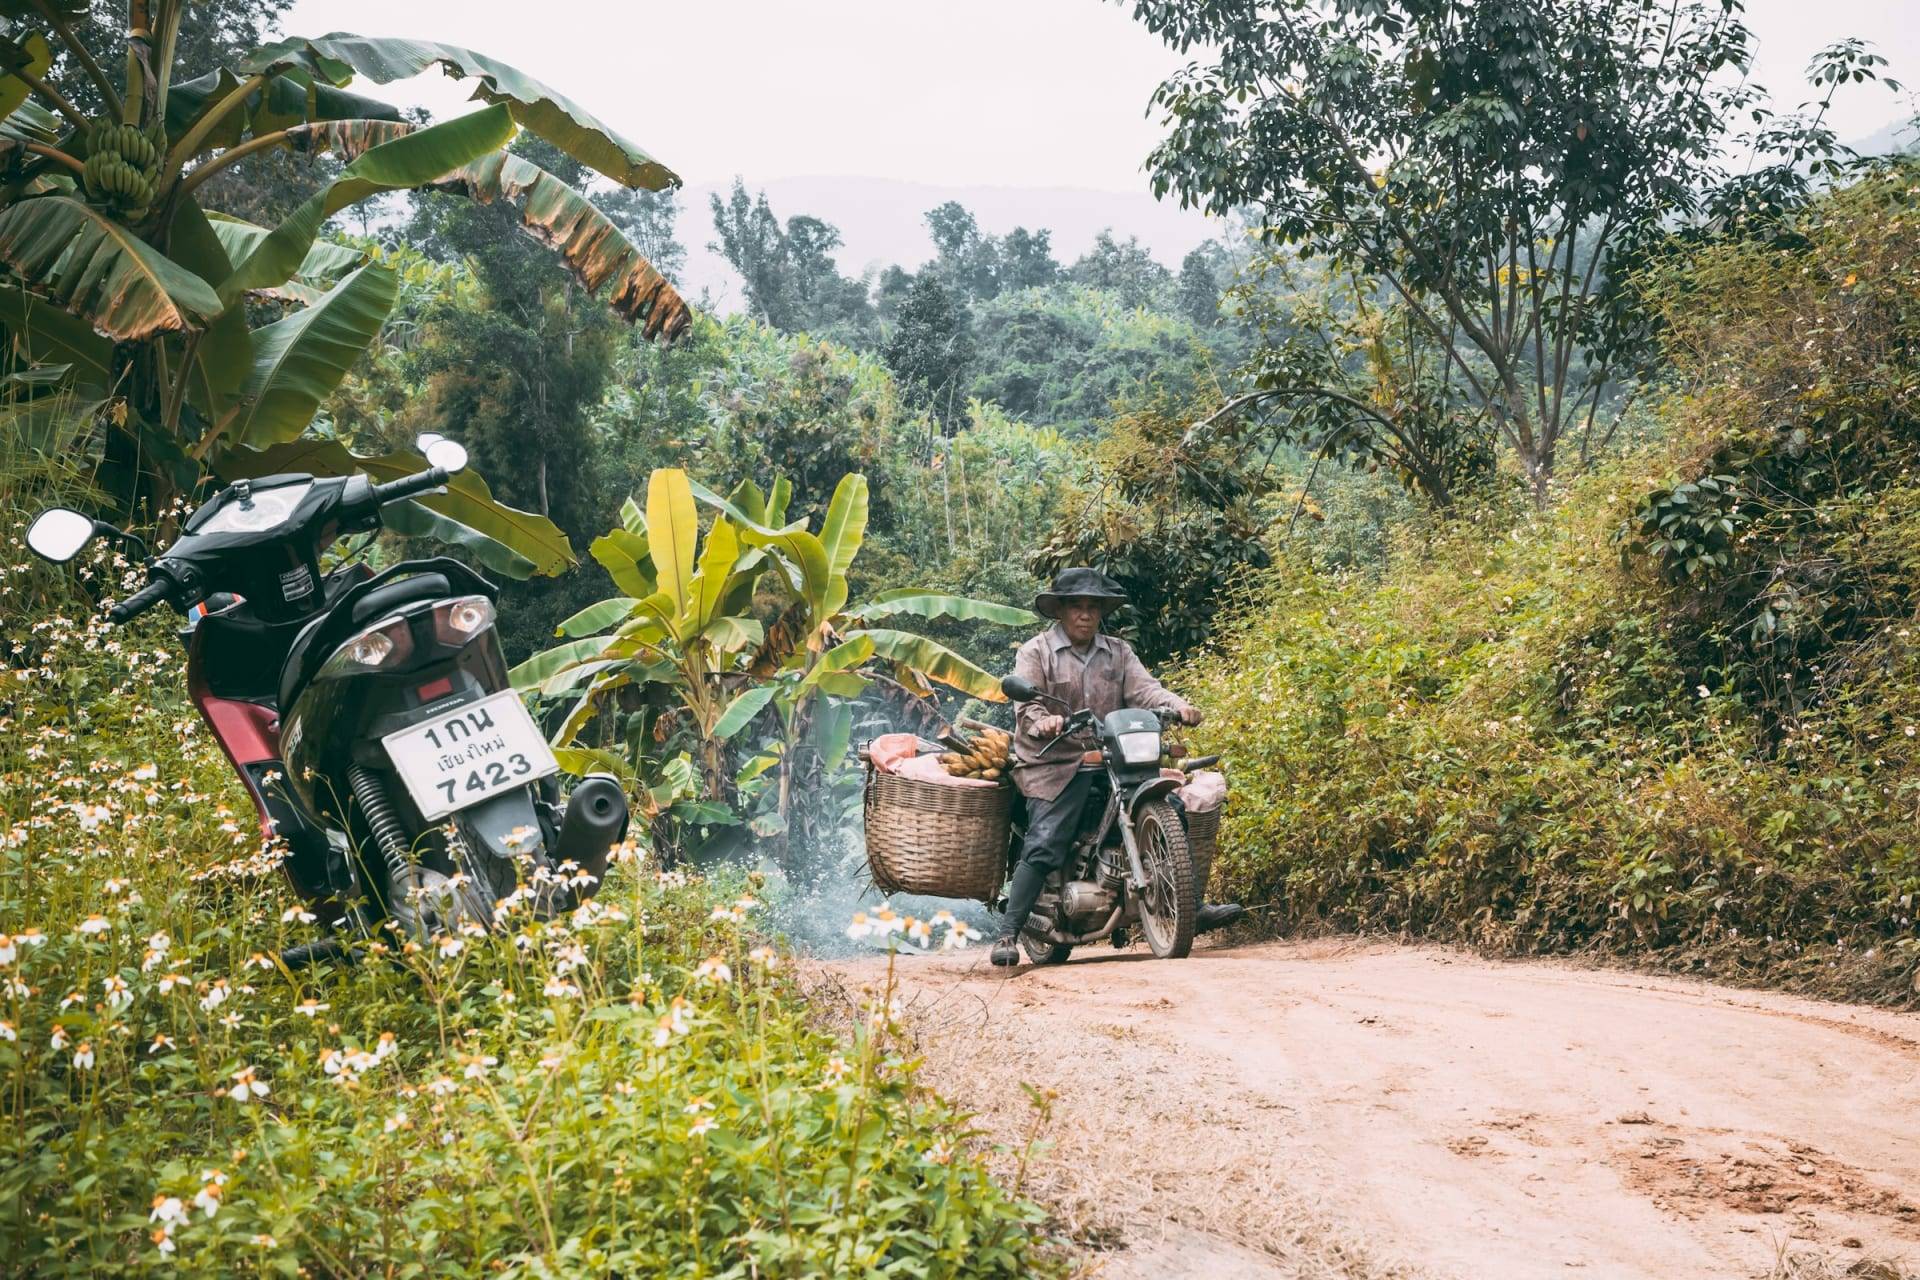
Motorcyclist on a forest road

Travel prep · step 2

Travel insurance that fits a long trip

Most travel insurance is built for a fortnight in the sun, sold in your own country, and stops the moment you have already left. That is the wrong shape for six months in Asia. We use SafetyWing, and below is exactly what it does, what it does not, and the one box you have to tick before you press buy.

Mountain road near Pai, northern Thailand

  • Sold to almost any nationality not tied to where you live
  • Buy it while you are already away you do not have to be home
  • $250,000 for medical care and no excess to pay first
  • Pay per four weeks stop it when you come home
Read this first

This is medical cover, not a full travel insurance

That distinction is the whole point, and it is where most people get caught out. SafetyWing is built to stop a hospital bill from ending your trip. It is not built to give you your money back when something goes wrong with the trip itself. Know which of the two you are buying.

What it does do

  • Hospital stays, surgery, nursing care and an ambulance, up to $250,000
  • Emergency evacuation if the nearest proper hospital is a flight away
  • Emergency dental, up to $1,000, for the tooth you break on something you should not have bitten
  • Your checked luggage if the airline loses it, up to $3,000
  • Getting you home, and the costs if you have to break off your trip, up to $5,000
  • Cover in more than 185 countries, and 30 days a year back in your own

What it does not do

  • Cancelling your trip before you go. Book a flight and then break your leg at home, and this policy gives you nothing back.
  • Anything you already had. Pre-existing conditions are excluded, and so are maternity care and cancer treatment.
  • Damage you cause. There is no liability cover here: not the scooter you scratch, not the shop window you ride into, not someone else's hospital bill.
  • Your phone and laptop, unless you tick the electronics add-on when you buy.
  • Anything you are paid for. Work a season behind a bar or teach diving for board and lodging and you are outside the policy while you do it.
  • Riding anything bigger than 50cc, unless you tick the adventure sports add-on. Read the next section, because this one catches nearly everybody.

None of that makes it a bad policy. It makes it a policy with a shape, and that shape happens to fit a long trip better than a fortnight policy does. You just have to know where the edges are before you are standing in a clinic in Krabi.

Before you buy

Which boxes do you have to tick?

Three questions, and you know which add-ons you need and what it comes to per four weeks. Do this before you buy, because the add-ons can only be chosen at the moment you take out the policy. You cannot add them later.

1 Are you going to ride a scooter?

Almost every rental scooter in Southeast Asia is 110cc or more, and above 50cc SafetyWing wants the adventure sports add-on.

2 Are you going to dive, or do anything else that gets the blood going?

Scuba is covered to the depth you or your instructor is licensed for, but only with the add-on. The same list covers kitesurfing, paragliding, skydiving and about forty other things. Whitewater rafting is the exception: SafetyWing does not cover it, not even with the add-on.

3 Are you carrying a laptop, camera or drone?

Electronics are not in the basic plan. With the add-on you are covered up to $1,000 an item, as long as you report the theft to the police within 24 hours.

The add-ons

Three boxes, and two of them matter to you

SafetyWing keeps the basic plan cheap by leaving things out and letting you put them back. That works, as long as you know what you are leaving out.

Adventure sports Almost everyone needs this

Covers scuba diving to the depth you or your instructor is licensed for, plus riding anything over 50cc, kitesurfing, paragliding, skydiving and around forty other activities, up to $100,000 over your lifetime. Whitewater rafting stays excluded, even with this add-on. It does not count in your own country, and it does not count if you are being paid to do it.

$10 per four weeks

Electronics theft If you carry a laptop

Laptop, camera, phone, tablet or drone, up to $1,000 an item and $3,000 per period, paid out on what the thing is worth now: it loses 2% of its value for every month since you bought it. You have to report the theft to the police within 24 hours and be able to show you owned the thing, so keep a receipt in your email.

around $10 per four weeks

United States cover

Only relevant if your route touches the United States. Healthcare there costs several times what it does anywhere else, which is why it sits outside the plan and costs about as much again as the plan itself.

around $53 per four weeks

Whatever you decide: decide it now. An add-on can only be chosen at the moment you take out the policy, and cannot be added to a policy that is already running. And they only exist on the plan that renews every four weeks: pick the fixed dates with the 10% discount and the adventure and electronics boxes are simply not there. This is the single most expensive thing to get wrong on this page.

The one nobody mentions

Your rental scooter is not in the basic plan

You will rent one. Everybody does: it is how you get to the waterfall, the viewpoint and the beach that the minibus does not go to. And the basic policy covers you on a moped up to 50cc, while the scooter they hand you in Pai, Ha Giang or Koh Lanta is 110cc, 125cc or 160cc. Above 50cc you need the adventure sports add-on, and there is no way to arrange that after the fact.

Sort this before you ride

  • Tick adventure sports when you buy, not later
  • Wear a helmet, every time, including the five minutes to the shop
  • Hold a licence for what you are riding, plus the international permit where the country asks for one
  • Stay off it if you have been drinking, because that voids the cover completely

And this stays yours, add-on or not

  • Damage to the scooter itself. The rental shop will ask you for it and the policy does not pay it.
  • Damage to anything else you hit, from a parked car to a fruit stall.
  • The hospital bill of anyone else involved. Your own care is covered, theirs is not.
  • Anything that happens while racing.
Rider in a white helmet in traffic
Ho Chi Minh City, Vietnam
What actually goes wrong

Four things that happen on this route

Not the dramatic ones. These are the four we have seen happen to people we were travelling with, and what the policy does with each.

Rider in a white helmet in traffic Adventure sports add-on You come off the scooter

Ho Chi Minh City, Vietnam

A sand track near Pai, a pothole in Saigon traffic, or an oil slick after the rain. Grazed legs, an x-ray and possibly a night in a clinic.

With the add-on your treatment falls under the $250,000 medical limit, and the evacuation cover pays to move you if the nearest decent hospital is a flight away.

Without the add-on, an accident on anything over 50cc is simply not covered. And no helmet means no claim, even with the add-on.

Drip bag on a stand in a hospital room Basic plan Dengue, and you are on a drip

On a drip

Dengue, a bad infection or food poisoning that will not shift. In Asia that usually means a private clinic, and a private clinic charges accordingly.

This is what the plan is built for: hospital stay, diagnostics, nursing care and the ambulance, up to $250,000, with no excess to pay first.

Ask for an itemised invoice in English before you leave the clinic. Claiming without one is slow and sometimes impossible.

Passengers on a bus at night Electronics add-on Your laptop goes missing on the night bus

Night bus, somewhere in between

You sleep from Hanoi to Hue. When you wake up the net beside your seat is empty.

With the electronics add-on you get up to $1,000 for the item, against what it is worth now rather than what you paid.

Report it to the police within 24 hours and get a copy. No report, no claim, and the report is far harder to get once you have moved on to the next town.

View of clouds from an aeroplane window Basic plan You have to go home at short notice

Home sooner than planned

Someone at home is seriously ill, or you are, and you have to break off the trip halfway.

Trip interruption pays up to $5,000 towards getting you back, and it is in the basic plan.

This is not the same as cancellation. Break your leg the week before you fly out and nothing here gives you your flight back: SafetyWing does not do cancellation at all.

The numbers

What it pays, up to what

The figures on your policy, in the currency they are written in. These are ceilings and not payouts: what you actually get back is what the care actually cost.

$250,000 Medical treatment and hospital admission
$100,000 Emergency evacuation, lifetime maximum
$1,000 Emergency dental
$3,000 Checked luggage the airline lost
$5,000 Breaking off your trip
$20,000 Repatriation in the event of death

The policy is written in US dollars and SafetyWing charges in US dollars. Everywhere else on this site we work in euros, but converting a policy limit would only make it unrecognisable next to your own policy document.

Where these numbers come from. Prices, limits and conditions come from SafetyWing's own product and help pages, checked on 15 September 2026. Amounts marked "around" are not on their price page and come from a secondary source, so treat those as an indication. Insurers change their terms quietly: your own quote is the number that counts. Euros are converted at 0.862 to the dollar, the rate on 13 September 2026, and are an indication rather than a receipt.

Call them before you spend anything

This is the one rule worth remembering. Before you run up a medical bill, before you book a flight home, before you agree to anything at a clinic: contact SafetyWing first. They can arrange payment directly with the hospital in a lot of cases, which saves you from putting several thousand on a card and hoping. Put the number in your phone before you leave.

Before you press buy

Nine things to have straight

Tick these off once and you will not have to think about your insurance again until you need it.

Remco and Anouk of Rebels on the Road
If you are wondering whether to bother

It is not compulsory, and you still want it

No country on this route asks to see a policy at the border. That is why plenty of people go without, and most of them come home fine.

The reason to have one is not the graze or the stomach bug. Those you can pay for out of your own pocket in Asia, and often it is cheaper than the excess at home. The reason is the small chance of the thing that costs more than your whole trip: a road accident that needs surgery, dengue that turns serious, a flight home with a doctor next to you. That is a five-figure bill, and it is the one that follows you for years.

Six months of Essential with the adventure sports add-on comes to roughly €400, about what two weeks on the road cost you. Set against what it is for, that is not the part of the budget to be clever about.

Get your price at SafetyWing

We earn a fee if you take out a policy. Your price is the same either way. How that works

One more thing

Questions we get a lot

Can I take it out if I have already left?

Yes, and that is one of the main reasons we use it. Most insurers sold in your own country want you to buy before you leave, and refuse you once you are abroad. SafetyWing does not: you can take it out mid-trip, from wherever you are. Cover starts from the date you choose, so anything that already happened is not covered.

Does it cover diving?

With the adventure sports add-on, yes, up to the depth you are licensed for, or the depth your instructor is licensed for if you are diving with one. Without the add-on it is not covered. Note the exclusion that catches people in our own line of work: if you are being paid to dive, or teaching it, you are outside the policy while you do it. A course you are paying for is fine, a job is not.

Do I really need the add-on for a scooter?

If it is over 50cc, yes, and in Southeast Asia it will be. Rental scooters there are typically 110cc to 160cc. On the basic plan a moped up to 50cc is included, and above that you need adventure sports. On top of that, a helmet and the right licence are conditions rather than suggestions: without them a claim fails even with the add-on.

Is there an excess?

No. Nomad Insurance Essential has no excess or deductible: you do not pay the first slice yourself. That changed in February 2024, so older reviews saying $250 are out of date. Check it in your own quote anyway, because this is exactly the kind of thing an insurer changes quietly.

What about the stuff I already have wrong with me?

Pre-existing conditions are not covered, and neither is maternity care or cancer treatment. If you have something ongoing, this is the point to get advice rather than to guess, because a claim that turns out to be related to it will be refused.

What is the difference with the Complete plan?

Complete is a proper health insurance rather than travel cover: routine appointments, check-ups and ongoing care are in it. It costs around three times as much and renews indefinitely. It makes sense if you are living abroad rather than travelling. For a trip of a few months, Essential is the one.

How do I claim?

Contact SafetyWing before you run up the bill where you can, because they will often settle directly with the hospital. Otherwise you pay and claim it back online with the itemised invoice. For theft you need a police report made within 24 hours and proof that the thing was yours.

What does it cost?

Essential is $62.72 per four weeks for ages 18 to 39, which is about €54. The adventure sports and electronics add-ons are roughly $10 per four weeks each. Older travellers pay more, and the amount you see depends on your dates and where you live, so get your own quote. Prices move: this one went up from $56.28 in the course of a year.

Do you earn anything if I use your link?

Yes. If you take out a policy through our link, SafetyWing pays us a fee and your price stays exactly the same. It is one of the ways this site pays for itself. It is also why we have written down at length what this policy does not do: a recommendation is only worth anything if you also hear the awkward part.

Next step

Insurance sorted. Now the paperwork

The other thing you want straight before you fly: which of your countries wants a visa, which wants a form, and which just stamps you in.

We earn a fee if you take out a policy. Your price is the same either way.